Emil Blaignan
  • Home
  • Research
  • CV
  • Blog
  • Personal

Research

Research

At UCLA Anderson, I work on empirical asset pricing research with Valentin Haddad and Tyler Muir, focused on high-dimensional stochastic discount factor estimation and how model complexity affects the investment opportunity set. Selected notes below.

A Variance-Hierarchy Ablation of the KNS Estimator
PYTHON ASSET PRICING RIDGE REGULARIZATION

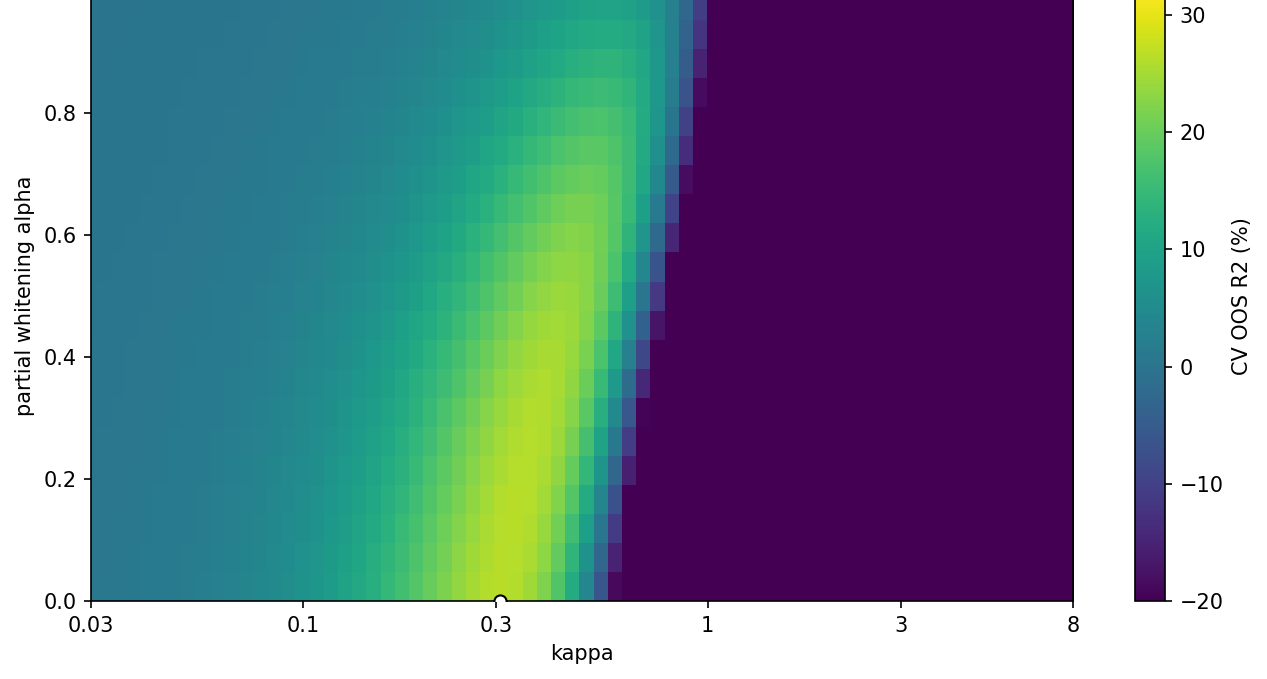
Ablation of the Kozak-Nagel-Santosh SDF estimator testing how much its cross-sectional pricing power depends on the covariance eigenvalue hierarchy. A partial-whitening continuum isolates finite-sample regularization from the population Sharpe ratio: whitening leaves the maximal Sharpe ratio invariant, but original-space CV R² collapses from 26.35% to 10.36% as the spectrum flattens, showing the variance hierarchy is load-bearing for the linear ridge estimator.

PDF Notes

May 2026

CKMS Replication and a Complexity Sweep of the Maximal Sharpe Ratio

PYTHON RANDOM FEATURES RIDGE REGRESSION

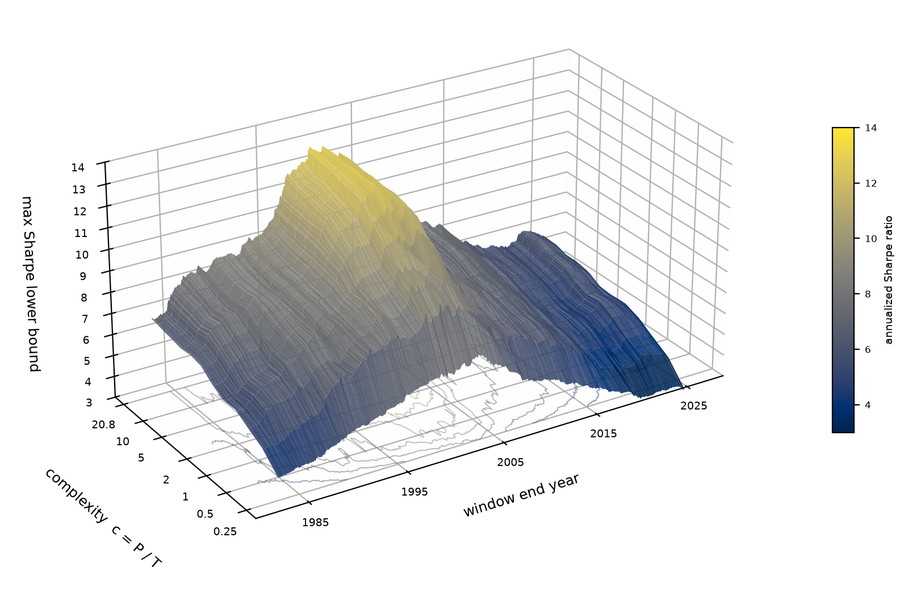
Replicates the CKMS bound on the population maximal Sharpe ratio on a rebuilt JKP equity pipeline, then runs a rolling complexity sweep from 121 linear characteristics to 5,000 random nonlinear features across 517 rolling 240-month windows. Finds a single dominant time-varying level (SVD share ≈ 0.98) with a roughly constant multiplicative gain from added model capacity, and a distinct pattern for mega-cap stocks.

PDF Notes

September 2026

Projects

Yield Curve Forecaster

PYTHON SQL NSS/AFNS

A quantitative fixed-income analytics toolkit for visualizing, forecasting, and analyzing treasury yields using advanced econometric models. Features Nelson-Siegel-Svensson curve fitting and dynamic term structure analysis.

GitHub

March 20th, 2025

Macro Drivers of S&P 500

R ECONOMETRICS BORUTA

A comprehensive econometric analysis identifying key macroeconomic drivers of S&P 500 returns using Boruta feature selection and multiple regression modeling. Explores non-linear relationships and provides robust statistical inference.

GitHub PDF Report

May 29th, 2025

A Variance-Hierarchy Ablation of the KNS Estimator

Ablation of the Kozak-Nagel-Santosh SDF estimator testing how much its cross-sectional pricing power depends on the covariance eigenvalue hierarchy. A partial-whitening continuum isolates finite-sample regularization from the population Sharpe ratio: whitening leaves the maximal Sharpe ratio invariant, but original-space CV R² collapses from 26.35% to 10.36% as the spectrum flattens, showing the variance hierarchy is load-bearing for the linear ridge estimator.

CKMS Replication and a Complexity Sweep of the Maximal Sharpe Ratio
Replicates the CKMS bound on the population maximal Sharpe ratio on a rebuilt JKP equity pipeline, then runs a rolling complexity sweep from 121 linear characteristics to 5,000 random nonlinear features across 517 rolling 240-month windows. Finds a single dominant time-varying level (SVD share ≈ 0.98) with a roughly constant multiplicative gain from added model capacity, and a distinct pattern for mega-cap stocks.

Yield Curve Forecaster

A quantitative fixed-income analytics toolkit for visualizing, forecasting, and analyzing treasury yields using advanced econometric models. Features Nelson-Siegel-Svensson curve fitting and dynamic term structure analysis.

Macro Drivers of S&P 500

A comprehensive econometric analysis identifying key macroeconomic drivers of S&P 500 returns using Boruta feature selection and multiple regression modeling. Explores non-linear relationships and provides robust statistical inference.